Mortgage Rates Expected to Stay Above 7% Through 2027
- An average 30 year mortgage rate of 7.3% from October through December 2026
- Rates staying above 7% through the end of 2027
As to how much relief buyers can expect, Fratantoni put it this way:
"We're going to come down from this spike in rates. The unfortunate news is, I don't think we're going to come down that far."
The biggest reason is inflation, which means rising prices across the economy. It's running above the Federal Reserve's 2% goal by a wide margin, and higher energy prices are a big part of the problem.
To fight inflation, the Fed raised its key interest rate last month for the first time in three years. MBA expects two more small increases:
- One in December 2026
- One in the first three months of 2027
Mortgage rates move with the 10 year Treasury yield, which is the return investors can earn on 10 year government bonds. Lenders use it as a guide when they set rates. MBA expects it to average 5.1% this quarter and stay near 5% through 2027.
How Buyers Are Adjusting to 7% Rates
Buyers who are moving forward are finding ways to lower their rate. MBA Deputy Chief Economist Joel Kan said two options are becoming more popular lately.
"The buyers who are still in the market are increasingly turning to ARM loans or paying points to lower their rates for the life of the loan. The ARM share of applications averaged almost 10% over the past month and MBA forecasts that it will remain over 9% through 2027."
Each option works a little differently:
- Adjustable-rate mortgage (ARM): You get a lower rate for a set number of years. After that, your rate can go up or down, so your monthly payment could rise by quite a bit.
- Mortgage points: You pay an upfront fee at closing to lower your rate. The lower rate stays with you for the life of the loan, and you'll need more cash at closing.
The right choice depends on how long you plan to stay in the home and how much cash you have for closing. A lender can run the numbers on both for you.
What This Means If You're Waiting to Buy
If MBA's forecast is right, waiting for rates to fall far below 7% could mean waiting until 2028 or beyond. A few other trends from MBA's forecast can help you plan:
- Home purchase activity is running about 9% below where it was in January.
- National home price growth has been in the 2% range. MBA expects it to slow in 2027 and pick up in 2028.
- MBA expects builders to start fewer new homes over the course of its forecast.
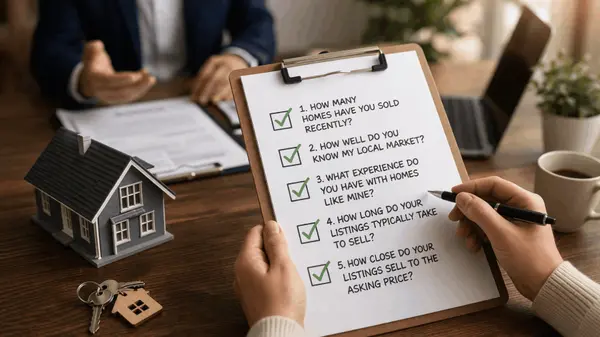
Questions to Ask When You Call Local Lenders
Rates and fees can vary from one lender to the next, so I encourage every buyer to talk with more than one. Bring these questions to each call:
- How much would it cost to buy points, and how many years would it take for the lower payment to make up for that cost?
- If I go with an ARM, how long does the starting rate last, and how high could my payment go after that?
- What rate and APR can you offer me on a 30 year fixed loan right now?
- What fees are included in you Loan Estimate?
- How long can I lock my rate, and what happens if rates change before closing?
Ask each lender for a Loan Estimate, a standard form that spells out your rate and closing costs. Laying them side by side makes it a lot easier to compare offers.
If your not sure which lenders to call first, I can help with that based on my own experience and from feedback I've received from clients who've worked with them.
Based on MBA's forecast, rates above 7% look likely to stick around for at least another year. Getting your loan questions answered early gives you a clearer picture of your budget before you start touring homes.
Recent Posts
"My job is to find and attract mastery-based agents to the office, protect the culture, and make sure everyone is happy! "
725 E. Mountain St., Kernersville, Carolina 27284, United States